Technological Transformation
For most of the past decade, Nigeria's technology story has been told almost entirely through fintech: Lagos as the fintech capital of Africa, unicorns like Flutterwave and Interswitch, and a startup ecosystem that consistently drew the largest share of continental venture capital by deal count. In 2026, that story is being rewritten on three fronts simultaneously. Nigeria has slipped from the top of Africa's funding league table even as its most valuable fintech, Moniepoint, cements unicorn status; a wave of hyperscale and mid-scale data-center investment is racing to catch up with submarine-cable capacity that has sat under-monetized for years; and a sweeping new digital-identity law signed in June 2026 is repositioning the National Identity Management Commission (NIMC) as the backbone of the country's entire digital-trust infrastructure. Together, these threads describe a market moving from consumer-fintech growth toward the deeper digital infrastructure layer — compute, connectivity, and identity — that underpins everything built on top of it.
A Funding Ecosystem That Has Fallen Behind on Value, Not Volume
Africa's tech funding recovery is real: according to Disrupt Africa's 2025 annual report, 178 African startups raised a combined $1.64 billion in 2025, a 46.2 percent increase over the $1.12 billion raised in 2024. Partech Partners' parallel 2025 Africa Tech VC Report, which counts both equity and debt financing, put total continental funding at $4.1 billion, up 25 percent year-on-year and driven substantially by record debt activity alongside more disciplined equity growth. Nigeria, however, fell to fourth place among African funding destinations in 2025, behind Kenya ($879 million), South Africa ($848 million), and Egypt ($561 million) — the first time in years it has not led the continent outright. Kenya, South Africa, Egypt, and Nigeria together still captured 72 percent of all African tech funding, so Nigeria remains firmly inside the continent's top tier, but the composition of its lead has shifted: Nigeria continues to generate the highest number of individual deals of any African market, yet trails badly on deal size, with the average Nigerian funding round sitting at roughly $1.6 million compared with Kenya's $6.9 million. Investors, per Disrupt Africa's analysis, concentrated 2025 capital into fewer, larger deals continent-wide, and Nigeria's deal-heavy, ticket-light profile has left it comparatively exposed to that shift toward selectivity.
May 2026 offered a snapshot of what that concentration looks like in practice: Nigerian startups raised approximately $58.5 million across the month's major disclosed deals, with just five companies — LemFi, BFREE, MAX, Sycamore, and Tomato Jos — accounting for roughly $57 million, or 97.4 percent, of the total. The sectoral spread of that capital (fintech, logistics, agritech, and enterprise technology) reflects a broader diversification analysts at Businessday NG and other outlets have flagged for 2026: Nigeria's next growth wave, they argue, may come less from consumer fintech, which is increasingly saturated and regulated, and more from enterprise software and the digital-infrastructure layer — the exact segment now attracting the country's largest capital commitments outside pure fintech.
Moniepoint's Unicorn Status and the Limits of Fintech-Led Growth
Moniepoint remains Nigeria's clearest fintech success story and a useful marker of how far the sector has matured. Having reached unicorn status in late 2024, Moniepoint now processes more than $250 billion in transaction value annually and serves over 10 million active users, with backers including Google, Visa, the International Finance Corporation, British International Investment (DPI), and LeapFrog Investments. Tracxn's July 2026 tally counts Nigeria's unicorn cohort at four companies, alongside Flutterwave, Interswitch, and Andela — a group that has not grown in headline count even as funding volumes elsewhere in the ecosystem have risen, reinforcing the sense that Nigeria's fintech layer has entered a more mature, consolidation-oriented phase rather than a unicorn-minting one.
The Data-Center Race: Catching Up to Submarine-Cable Capacity
Nigeria's connectivity infrastructure has, for several years, outpaced its compute infrastructure. Google's Equiano cable, based on space-division multiplexing technology with 12 fiber pairs and a design capacity of roughly 144 terabits per second — about 20 times the capacity of the previous generation of West African cables — landed at the OADC Lagos cable landing station in April 2022. Meta's 2Africa system followed with two separate Nigerian landings: Bayobab (formerly MTN GlobalConnect) brought it ashore at Lekki, Lagos, in February 2024, while MainOne landed a second branch in Akwa Ibom State the same month, making Akwa Ibom the only Nigerian 2Africa landing point outside Lagos. Lagos alone retained 29.72 percent of Nigeria's national internet-infrastructure revenue in 2025, a concentration the Equiano and 2Africa landings, a dense local ISP presence, and the city's role as financial-sector headquarters all reinforce.
Data-center capacity is now racing to catch up with that cable bandwidth. Rack Centre launched a 12-megawatt data center in April 2025, expanding one of Nigeria's established interconnection hubs. Equinix separately announced plans for a $22 million data center build in Lagos. The largest single project disclosed in 2026 is Kasi Cloud Ltd., a next-generation interconnection and data-center platform backed by Nigeria's sovereign wealth fund, which broke ground on a $250 million hyperscale data-center campus in Lekki, Lagos — explicitly designed to give Nigeria's fintech unicorns, including Flutterwave, Moniepoint, and Interswitch, the low-latency local infrastructure their transaction volumes require. Analysts covering the buildout note a persistent tension underlying all of this investment: Nigeria's power grid remains a binding constraint on hyperscale ambitions, meaning data-center operators must typically pair new campuses with dedicated, often gas- or diesel-backed generation capacity rather than relying on grid supply alone. Sector forecasts nonetheless expect continued expansion in demand for data centers, cloud services, cybersecurity platforms, and fiber connectivity as Nigerian businesses adopt AI and other digital tools at scale, creating a secondary wave of infrastructure-focused startup opportunity distinct from the earlier consumer-fintech boom.
A New Digital-Identity Law Repositions NIMC as Critical Infrastructure
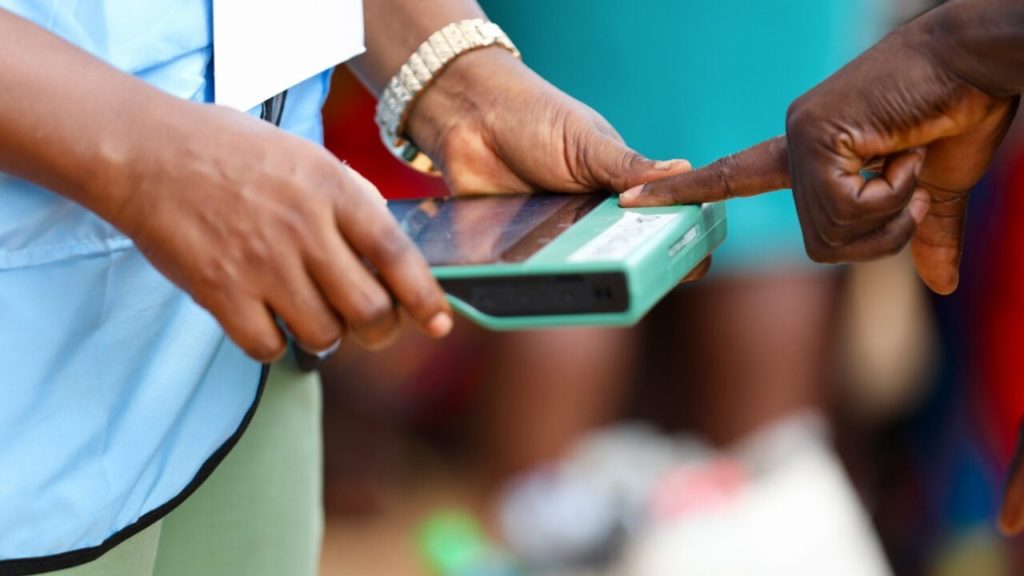
The most structurally significant policy development of 2026 may be the NIMC Act, which President Bola Tinubu signed into law on June 26, 2026, replacing the original 2007 NIMC Act. The new legislation substantially expands the National Identity Management Commission's mandate, giving it explicit authority over digital identity, cybersecurity, authentication, data protection, and digital-trust infrastructure — and, critically, establishes NIMC as the Root Certification Authority for Nigeria's National Public Key Infrastructure and broader Digital Public Infrastructure. That designation places NIMC at the center of the cryptographic trust architecture that will underpin future e-government services, digital signatures, and secure authentication across both public and private platforms. The law also expands the legal recognition of the National Identification Number (NIN) across taxation, banking, pensions, healthcare, voting, and business registration, formalizing NIN as the default identifier across sectors that had previously maintained separate identity systems.
NIN enrollment itself has continued to scale, reportedly reaching 136 million registered numbers in 2026 — a substantial base for a country with a population estimated at roughly 230 million, though coverage gaps and duplicate or inactive records remain acknowledged challenges. TechCabal's coverage of the enrollment drive noted that NIMC needed to register 3.3 million Nigerians per month to meet earlier 2026 targets, illustrating the operational scale required to close remaining gaps. A parallel critique from Technext in May 2026 argued that Nigeria has built substantial identity infrastructure but has lagged on identity usability — the friction citizens experience when actually using their NIN to access services — suggesting that the new Act's success will be measured less by enrollment numbers than by how seamlessly the NIN functions as a practical authentication tool across banks, tax authorities, and government agencies in the months ahead.
What the Three Threads Have in Common
Funding concentration, data-center construction, and digital-identity legislation might appear to be separate stories, but they point toward the same underlying shift: Nigeria's technology sector is moving from a phase defined by consumer-facing fintech adoption toward one defined by the infrastructure layers — compute capacity, trusted identity, and enterprise software — that let that earlier fintech growth scale further and let new categories of digital business emerge. Kenya, South Africa, and Egypt overtaking Nigeria in headline funding totals in 2025 does not indicate a shrinking Nigerian tech sector; deal count data suggests the opposite. It indicates a market whose center of gravity is shifting from many small, fintech-heavy raises toward a smaller number of larger, infrastructure- and enterprise-oriented investments — precisely the kind of capital the Kasi Cloud data-center project, the NIMC Act's digital-trust framework, and Nigeria's next wave of enterprise-software startups are now positioned to absorb.
Outlook
Nigeria enters the second half of 2026 as a technology market in transition rather than in decline. Its fintech unicorns remain the most valuable and widely used on the continent, its submarine-cable capacity is now finally being matched by serious data-center investment, and its new digital-identity law gives the country a more coherent legal foundation for digital public infrastructure than it has previously had. The open questions are execution questions: whether power constraints slow the data-center buildout relative to announced timelines, whether NIMC can convert 136 million NIN registrations into genuinely usable authentication across banking and government services, and whether Nigerian founders can successfully redirect investor attention from consumer fintech toward the enterprise and infrastructure software that regional peers are increasingly capturing. How those questions resolve over the next twelve to eighteen months will determine whether Nigeria reclaims its position atop Africa's funding tables or settles into a more infrastructure-focused, second-order role within a diversifying continental tech landscape.
Published By | Tech Wiz