Written By | Staff Writer
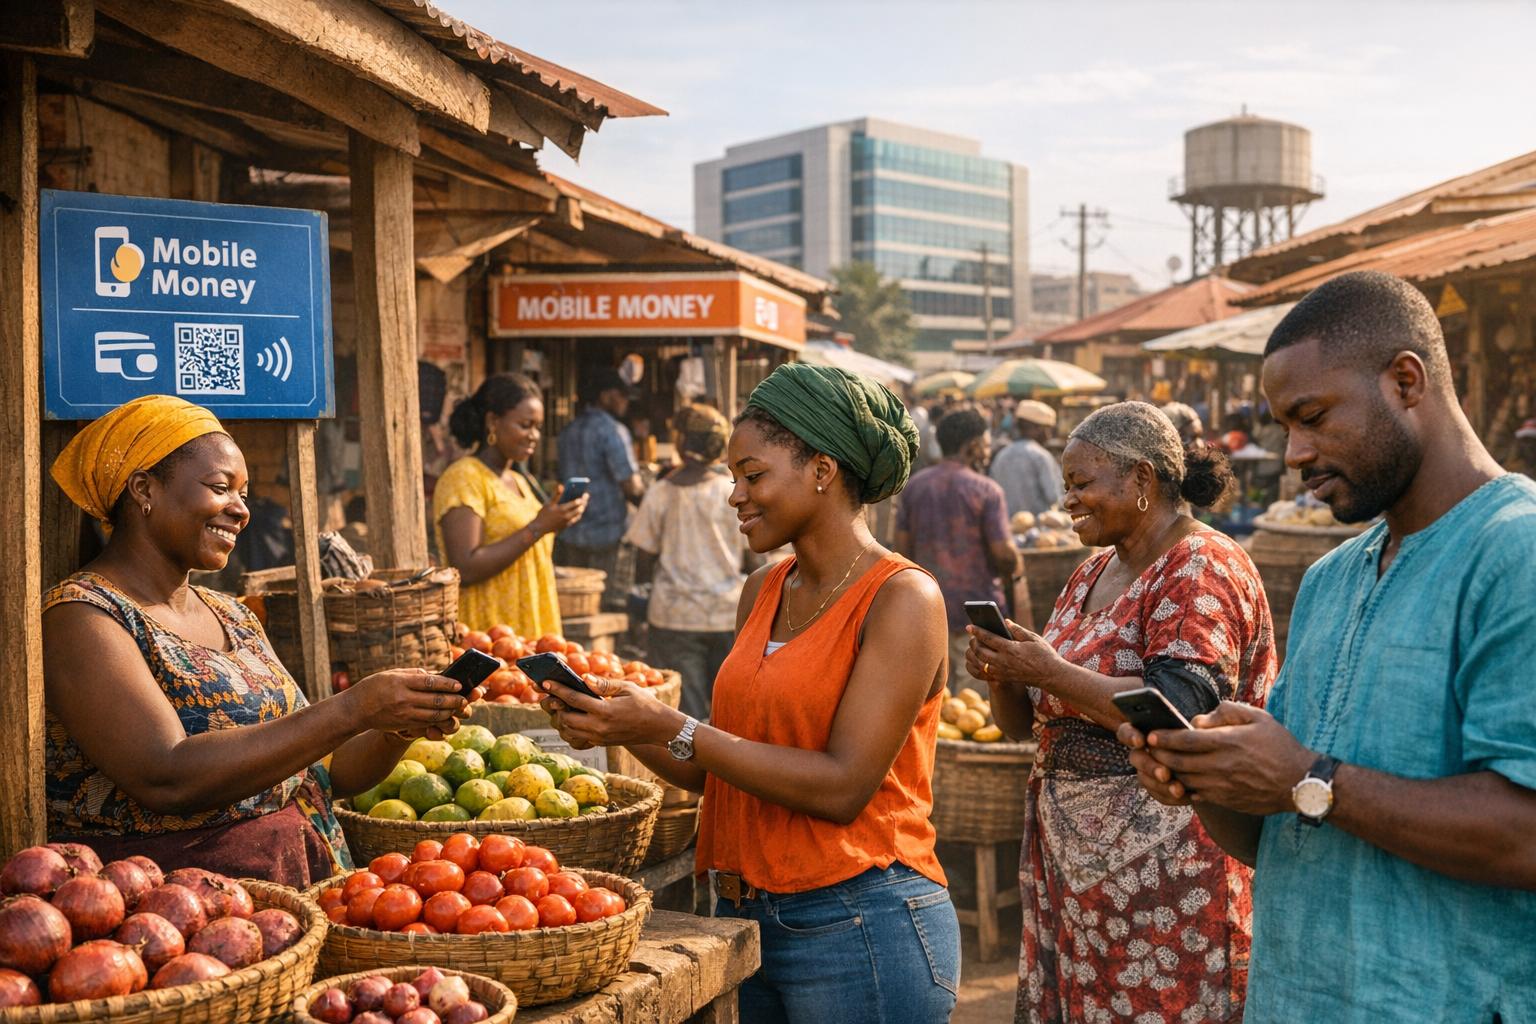
Malawi government's Digital Economy Strategy 2021-2026 set a target of reaching 80% internet access by 2025, up from roughly 14% in 2021
Malawi has spent the past five years running two parallel digital projects at once: laying the physical fibre that carries connectivity, and building the software and institutional layers — mobile money interoperability, a national digital identity, a modernized payment switch — that determine whether that connectivity actually reaches people. In 2026, both tracks are visibly advancing, but the country's own numbers show how far it still has to go. The government's Digital Economy Strategy 2021-2026 set a target of reaching 80% internet access by 2025, up from roughly 14% in 2021. Reporting this year from Broadcast Media Africa puts actual internet penetration at only about 20%, with fixed broadband coverage around 35% — a gap between ambition and delivery that now frames a new, more targeted push toward 80% access by 2030 rather than 2025.
A $180 Million Bet on Fibre and Skills
The centerpiece of Malawi's infrastructure push is the continuation of its national fibre backbone project, implemented in partnership with Huawei. President Lazarus Chakwera launched the second phase of the project, which is laying close to 3,000 kilometres of fibre-optic cable and is designed to connect more than 100,000 businesses and homes across the country, according to reporting from Developing Telecoms and ITWeb Africa. In 2026, that partnership was substantially expanded: Malawi and Huawei signed a $180 million agreement described by Africa.com as one of the largest single ICT investments in the country's recent history. Beyond cable and equipment, the deal includes a skills component — Huawei's 2026 ICT Development Programme is training 500 young Malawians in advanced ICT skills, an explicit attempt to build a local technical workforce capable of maintaining and extending the network rather than depending indefinitely on foreign contractors. The Ministry of Information is now also moving to accelerate Phase III of the backbone project, with an explicit focus on ensuring that falling bandwidth costs actually reach rural districts rather than concentrating in Lilongwe and Blantyre, per Digital Watch Observatory's coverage of the strategy.
A Mobile Money Duopoly Still Doing the Heavy Lifting
With formal banking still reaching a minority of the population — an estimated 25% of adults hold a formal bank account, according to 2026 reporting compiled by Transfi — mobile money remains Malawi's primary financial infrastructure. The Fintech Times' 2026 landscape review describes a market still shaped by a duopoly between Airtel Money and TNM Mpamba, both built on dense networks of local agents rather than bank branches, serving customers in lakeshore and rural districts where, as one industry analysis put it, the agent who knows a customer by name is often the real point of identity verification rather than a back-office compliance process. Around this duopoly, an estimated 20 fintech and digital financial services providers have emerged, most concentrated in payments rather than lending or insurance, reflecting a broader pattern across the sector: telecom-led innovation supported by banks, rather than an independent venture-backed startup wave of the kind seen in Nigeria or Kenya.
PayChangu and the Interoperability Push
One of the more notable developments bridging Malawi's fragmented payment rails is PayChangu, a domestic platform that integrates Airtel Money, TNM Mpamba and local bank cards into a single payment layer. AllAfrica reported in mid-2026 on PayChangu's role in enabling fast, transparent support for stranded Malawians, highlighting how the platform allows contributions to reach recipients from anywhere in the country within seconds — a capability that matters in a market where mobile money and bank rails have historically operated as separate, poorly interconnected systems. That interoperability push is being reinforced at the regulatory level: the Reserve Bank of Malawi's National Payment System Act, in force since 2017, already made it mandatory for payment service providers to connect to the National Switch (NatSwitch), and commercial bank customers have more recently gained access to instant electronic funds transfers through the same rail, according to reporting from The Nation.
Modernizing the Rails: NatSwitch and the RBM's 2026-2030 Vision
The Reserve Bank of Malawi unveiled a Payments System Vision covering 2026 to 2030, according to coverage from GovPing, setting a multi-year roadmap for further modernizing the country's payment infrastructure. Underpinning that vision is a concrete infrastructure project: the African Development Bank is financing a Support for Digitalization, Financial Inclusion and Competitiveness (DFIC) project that includes a systems upgrade of the National Switch itself, per AfDB procurement documentation. Together, the regulatory vision and the AfDB-financed upgrade point to an effort to move NatSwitch from a basic interoperability layer toward a more resilient, real-time settlement backbone capable of supporting the volume of mobile-money and bank transactions Malawi is generating as digital payments usage grows, particularly in rural areas that had previously been excluded from both banking and reliable mobile coverage.
Digital Identity: The NRB's National Rollout
Malawi's National Registration Bureau (NRB) is now at an advanced stage of rolling out a national digital identity system, with domestic outlets including The Nation and CAJ News Africa reporting a planned launch as early as September 2026, following a successful pilot of a digital ID wallet. The ambition, as described by TechAfrica News and MobileID World, is to make national identity verifiable directly on smartphones, a shift expected to accelerate financial inclusion — a direct link to the mobile-money duopoly described above — while reducing the long-term cost of producing physical ID cards. The NRB's work has already attracted international recognition: Malawi received the WSIS Forum 2026 Award in the E-Government category for a Digitally Signed Biometric QR Verification Platform, developed by the NRB with technical support from the UN Development Programme. The system combines cryptographically signed QR codes generated from the National Registration and Identification System (NRIS) with biometric authentication, enabling identity verification that works both online and offline — a design choice that matters directly in a country where reliable connectivity is still concentrated in urban centers.
Agritech and the "Missing Middle" in Rural Finance
Digital transformation in Malawi is also being extended into agriculture, where the Digital Economy Strategy 2021-2026 explicitly calls for greater use of the Internet of Things, smart-farming tools, open data and online platforms. The most concrete recent step came in May 2026, when Ecobank Group and the Alliance for a Green Revolution in Africa (AGRA) signed a memorandum of understanding at the Africa Forward Summit in Nairobi, creating a blended-finance and risk-sharing framework aimed specifically at Malawian agribusinesses caught in what the two organizations describe as the "missing middle" — too large for microfinance, too risky by conventional standards for commercial bank lending, according to reporting by Malawi24. Separately, the UN Technology Bank for the Least Developed Countries has begun formal engagement in Malawi, working with government and research institutions on science, technology and innovation policy that includes support for agricultural technology adoption, per Tech Review Africa.
Outlook
Malawi's digital transformation in 2026 reads less like a single breakthrough and more like several infrastructure and institutional projects converging at once: a Huawei-built fibre backbone entering its next phase, a payments regulator modernizing its core switch, a mobile-money duopoly being stitched together by third-party interoperability platforms, and a national digital ID moving from pilot to nationwide launch. The country's own strategy documents are candid about the gap between ambition and delivery — a 2025 internet-access target that landed closer to 20% than 80% is a reminder that infrastructure announcements and rural adoption do not move at the same speed. Whether the 2026-2030 push closes that gap will depend less on any single flagship project than on whether fibre, payment rails and digital identity keep reinforcing each other in the way this year's developments suggest they are starting to.



