Written By | Staff Writer
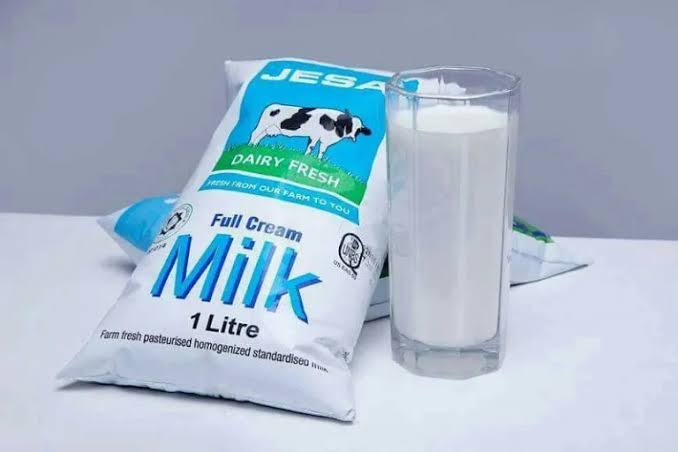
JESA's stock-out notice lands in the same week the region runs dry - exposing a dairy sector with a surplus at the national level, a crisis at the farm gate, and a border it cannot cross
Agriculture
A notice from Busunju
The statement was short and apologetic. “We are experiencing a temporary shortage due to the prolonged dry season, which has affected all dairy farming communities and led to reduced milk production,” JESA Farm Dairy told its customers, asking for patience and promising that product quality would not slip. The company, one of Uganda's best-known dairy brands, said the dry conditions had cut pasture and water at its Busunju farm and across its network of out-grower farmers in central Uganda. It did not say when normal supplies would resume.
Taken on its own, a processor running short of fresh milk in the September dry season is unremarkable. Taken alongside what is happening in Kenya, Rwanda and western Uganda in the same week, it is something closer to a diagnosis - and the diagnosis is not what most people would expect. Uganda is not short of milk. It is short of a way to move it.
The national numbers say surplus
Uganda produces an estimated 5.4 billion litres of milk a year, roughly 15 million litres a day. On the arithmetic that matters to the Ministry of Agriculture, Animal Industry and Fisheries, that is more than enough to supply the domestic market and keep the country's processing plants running at capacity, even with fodder declining. Production has climbed steeply over the past decade, from about 2.5 billion litres in 2017/18, and dairy export earnings rose from Shs276 billion to Shs358 billion between 2020/21 and 2022/23. Registered processors grew from 130 in 2022 to 160 in 2024; milk collection centres went from 483 to 729.
Ronald Tumukunde, Chief Executive of the Uganda Dairy Farmers Association, says the dry spell has been felt on Ugandan farms but that the decline in production has been modest. Benson Mwangi, General Manager of Brookside Dairies Uganda, is blunter about the contrast with the neighbours: “It's a question of demand and supply. In Kenya, the demand is huge unlike in Uganda where milk supply is more than enough.”
And yet the shelves at JESA are thin.
What the national average hides
The gap between the aggregate and the anecdote is where the real story sits. National production figures average across a country in which the dry spell has fallen very unevenly.
In Ntungamo district, daily output has dropped to roughly 40,000 litres from as much as 90,000 during the rainy season - a fall of more than half - as drought has stripped pasture and water sources and foot-and-mouth disease has moved through herds. Mbarara, the self-styled City of Milk and Honey, saw daily collection collapse from about 20,000 litres to between 5,000 and 8,000 litres last month, with retail prices roughly doubling from Shs1,200 to Shs2,500 a litre. The cattle-corridor districts of Ankole, greater Masaka and Ntungamo - precisely the areas that supply the processing plants - are the ones being hit hardest.
A processor whose out-growers sit in central Uganda, as JESA's do, cannot easily be rescued by a national surplus concentrated somewhere else, in a country where cold-chain logistics remain thin and where a litre of raw milk has a few hours of usable life without one.
The weather was forecast. The Ministry of Water and Environment's June-July-August 2026 seasonal outlook projected near-normal to below-normal rainfall across most of the country with warmer-than-average temperatures, attributing the suppression to warm sea surface temperatures in the equatorial central and eastern Pacific, alongside the Madden-Julian Oscillation and the position of the Inter-Tropical Convergence Zone. The southwestern highlands, the Rwenzori sub-region and central-western districts were all flagged for below-normal rainfall. What was not forecast is that the dry spell, which began around May and was expected to ease by July, would still be running in September.
The region is drier still
Across the border the same weather has produced a fuller-blown crisis. In Kenya, formal milk deliveries to processors fell 3.7 percent from 84.4 million litres in June to 81.3 million litres in July, and Kenya Dairy Board Managing Director William Maritim has said preliminary August indications suggest a further decline. Supermarkets in Nairobi have rationed purchases to fewer than five packets; Brookside, New KCC, Tuzo and Mt Kenya have disappeared from some shelves entirely.
The Consumer Federation of Kenya has demanded emergency intervention. “Cofek is deeply concerned by the continuing decline in formal milk intake and the resultant strain on retail prices,” said Secretary-General Stephen Mutoro, calling on the National Treasury to waive import duty and VAT on yellow maize, soya and other dairy-meal inputs. Kenyan feed costs have risen roughly 45 percent, and daily yields per cow have fallen from seven to nine litres down to four or five.
Rwanda is worse off again. Milk hubs in Nyagatare and the wider Eastern Province have seen production plunge by more than half; supplies from some farmer groups dropped from 90,000 litres to 40,000 at the peak of the shortage from July. A litre in Kigali now retails at about $0.94. Kigali also absorbed a mid-year Rift Valley Fever outbreak that triggered movement and trade restrictions on meat and milk. “We have not experienced this kind of dryness in a long time. The situation is so bad that we have lost many animals,” Gatsibo farmer John Ruyange told The EastAfrican.
Two large, adjacent, cash-paying markets are short of milk. Uganda has a surplus. Almost none of it is moving.
The border that will not open
The reason is not weather. It is paperwork.
Samson Mpiira, Head of the Dairy Development Department at Uganda's Ministry of Agriculture, says regional trade barriers are the main reason Uganda's surplus cannot ease shortages elsewhere in the East African Community. Mr Mwangi of Brookside Uganda describes export-permit restrictions that leave Ugandan processors hunting for alternative regional markets that cannot match Kenya's consumer base. His question is the one the whole sector is asking: “We are in the East African Community. Surely, do I need a permit to sell milk to a neighbour?”
The history behind that question is long and bad-tempered. Uganda and Kenya have fought recurring “milk wars” over non-tariff barriers for years; when Kenya recorded a surplus last year and stopped importing, Ugandan dealers protested. Uganda has since stopped exporting raw milk altogether, shifting to pasteurised milk, powder and other value-added products - a sensible move commercially, but one that makes Ugandan supply harder to substitute into a market like Rwanda's, where demand is specifically for raw milk.
Tanzania, meanwhile, has quietly done the opposite of liberalising and come out ahead. National production has grown 40 percent in six years, from three billion litres in 2019/20 to more than 4.2 billion litres in 2025/26, on the back of an import policy that raised duties and protected local processors. Tanzania has avoided shortages this season.
What it means for Ugandan farmers
For the farmer in Ntungamo watching output halve while the price of a litre in Kigali sits near a dollar, the lesson of this dry season is uncomfortable: the constraint on Ugandan dairy incomes is no longer productivity. Uganda has already won the production argument. The constraint is market access - permits, mutual recognition of standards, and the cold chain and powder capacity that would let a wet-season surplus be stored and sold into a dry-season shortage three months and one border away.
That points to three practical priorities. First, dry-season fodder: silage, hay banks and water-for-production investment are what turn a 50 percent seasonal collapse into a 15 percent one, and they are cheaper than the milk they save. Second, processing capacity for storable products - powder in particular - so that surplus has somewhere to go other than spoilage. The National Planning Authority has already identified milk powder exports as a strategic opportunity. Third, and hardest, a negotiated end to intra-EAC dairy non-tariff barriers, which will require political attention at a level above the Dairy Development Authority.
There is also a warning in the seasonal outlook. The Ministry of Water and Environment has forecast above-normal rainfall between August and December on a weak-to-moderate El Nino signal, and Kenya's dairy board is banking on October-December rains to restore pasture. If those rains arrive, the regional shortage will ease, Kenyan demand for Ugandan milk will fall away again, and the window in which Uganda's surplus was worth the most will have closed unused - exactly as it has in previous cycles.
JESA's shortage will pass. The Busunju herd will find grass again. But the notice the company sent its customers is a small piece of evidence for a larger and more durable problem: Uganda has built a dairy industry that can produce 15 million litres a day and a trading environment that cannot reliably sell them.



