Written By | Staff Writer
A Ugandan startup's $50,000 win for AI-driven lending lands in a country where credit reaches almost no one who actually grows food. The prize is small. The problem it points at is not.
Agriculture
A win in Kigali
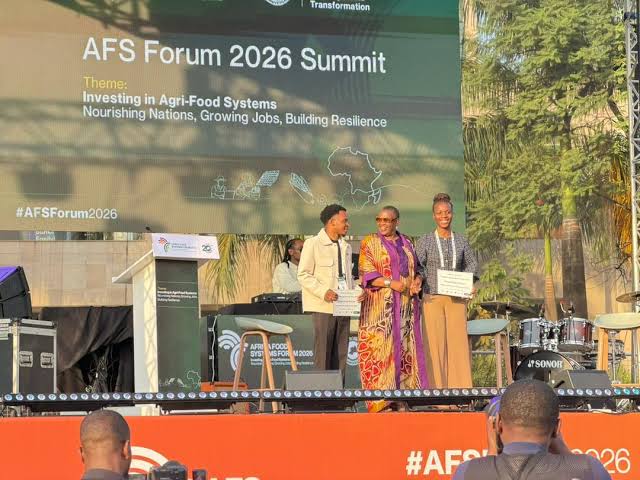
When the Africa Food Systems Forum wrapped up in Kigali on 4 September after five days of ministers, financiers and agribusiness executives arguing about how to feed a continent, the closing headline out of Uganda was not about a policy or a tonnage figure. It was about a piece of software.
SANDI AI Technologies, a Ugandan artificial-intelligence startup founded by Sandra Nabakka, was named the female-led grand prize winner of the 2026 GoGettaz Agripreneur Prize, taking US$50,000 — roughly Shs190 million — for a system that assesses smallholder farmers for loans without requiring the conventional collateral that keeps most of them out of the formal credit market. The competition, run by Generation Africa, awards two grand prizes of equal value each year, one to a female-led venture and one to a male-led venture, from a total prize pool of US$160,000. SANDI AI beat agrifood ventures from across the continent to take the female-led award.
"Farmers should not be limited by systems that were not designed around their realities," Nabakka said after the announcement. "Technology gives us an opportunity to understand farmers better, recognise their potential, and create pathways that allow them to access the resources they need to grow." Her stated ambition is to make access to finance "smarter, fairer, and more inclusive."
By the standards of Ugandan agricultural finance, Shs190 million is a rounding error. Uganda Development Bank disbursed Shs502.2 billion to 112,392 borrowers in its most recent reporting period; the European Investment Bank's credit line with Centenary Bank is worth Shs428 billion. Against those numbers, a $50,000 prize barely registers. That is precisely why it is worth writing about. The prize is not the story. What the prize was awarded for is.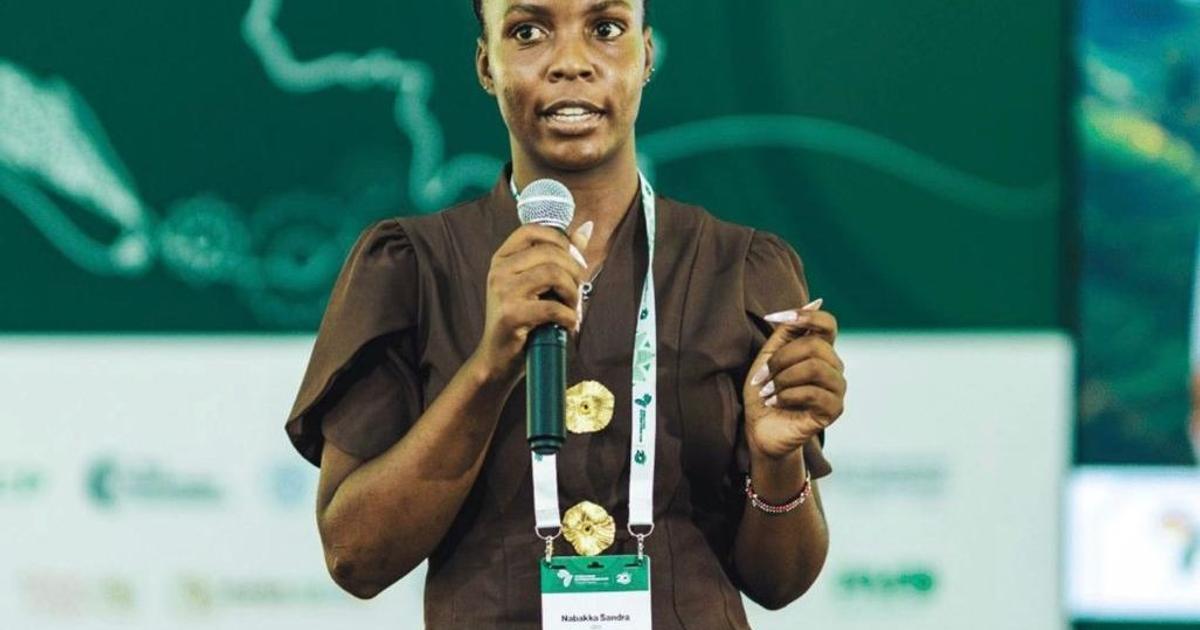
Nabakka
The collateral trap
African agriculture has a credit problem that has proved almost immune to money. According to figures from the African Development Bank cited in coverage of the award, only about 6 per cent of smallholder farmers on the continent have access to credit, and lending to agriculture accounts for less than 5 per cent of banks' loan books in many African countries — in a sector that employs the majority of the population.
The mechanics of that exclusion are not mysterious. A commercial lender assessing a loan application looks for three things: a documented income history, a fixed asset to secure the loan against, and a repayment profile that fits the bank's own funding costs. A typical Ugandan smallholder fails all three tests. Income arrives twice a year, in lumps, and is undocumented. Land is frequently held under customary or kibanja tenure without a title a bank will accept. And the crop cycle means the farmer needs money in March and can only repay in September — a shape that does not fit a standard amortising loan.
So the lender says no, or prices the loan so high that saying yes is worse. Uganda's central bank has held the Central Bank Rate at 9.75 per cent, and commercial lending rates sit well above that.
The policy response for two decades has been to push more money at the problem from above: the Agricultural Credit Facility, aBi Finance, the Parish Development Model, the Netherlands' recent Shs8 billion addition to a smallholder credit fund, the World Bank's AgriConnect Compact. Each of these adds supply. None of them changes the underwriting question — how does a lender decide whether this particular farmer, with no title and no payslip, is good for the money?
What alternative scoring actually does
That underwriting question is what SANDI AI says it is answering. The company describes its approach as combining artificial intelligence with agricultural data to build a picture of a borrower's potential rather than judging them against requirements they cannot meet — assessing farmers for loans that do not require conventional collateral, and connecting them to lenders on that basis.
The logic is familiar from consumer fintech, where mobile-money histories and airtime patterns have been used for a decade to score borrowers with no bank account. Applied to farming, the inputs get more interesting: satellite imagery of a plot across seasons, sub-county rainfall records, historical yields by crop and variety, nearby market prices, agro-dealer input purchases, aggregator delivery volumes. Together these can say something meaningful about whether a farmer will have money in November — without anyone producing a land title.
Uganda already has more of this data than it can use. The Uganda Agriculture Insurance Scheme reached a million insured farmers using satellite index products, which means somebody is already modelling weather risk down to the plot. NARO holds yield data by variety and agro-ecological zone. Mobile money penetration is deep, and aggregators keep delivery records. The raw material exists; what has been missing is anyone assembling it into something a loan officer can act on in five minutes.
Three reasons for caution
None of which means an algorithm solves this. There are at least three reasons to hold the enthusiasm at arm's length.
The first is that scoring is not lending. A model that says a farmer is creditworthy still needs a balance sheet behind it willing to take the risk, at a price the farmer can pay. Uganda's banks are short of appetite for agricultural risk and short of long-tenor, patient funding to match a crop cycle. The Uganda Bankers' Association has set a target of Shs490 trillion in patient capital by 2040 against a current stock of around Shs28 trillion — an acknowledgement that funding, not assessment, is the binding constraint.
The second is that the data can be wrong in ways that hurt. Uganda's 2026 season has been a case study in why: a drought that ran from May, an abrupt reversal into an above-normal rainfall outlook for August to December, crop failure across Acholi and Karamoja, and a coffee crop that lost buds to rain and then wilted in the dry spell. A model trained on historical yields will systematically under-score farmers in districts that have just had a bad run, at exactly the moment credit would help most. Algorithmic scoring is pro-cyclical unless it is deliberately designed not to be, and pro-cyclical credit in a climate-shocked farming system is a mechanism for making bad years worse.
The third is regulatory. Uganda is already struggling to supervise the tier just below the banks — only a handful of roughly ninety eligible SACCOs have been licensed ahead of a 30 September Bank of Uganda deadline. Digital credit scoring for farmers sits in an even thinner regulatory space: data consent, model transparency, what recourse a farmer has when an algorithm declines them, and how aggressively a lender may collect are largely unanswered questions. Kenya's experience with digital lending and over-indebtedness is a cautionary tale Uganda has watched from a distance, and will not watch indefinitely.
Why it still matters
Set against those caveats, the case for taking the win seriously is straightforward. Agriculture contributes roughly 26 per cent of Uganda's GDP, and virtually every productivity intervention the government is currently pursuing — the 173,913 bags of fertiliser flagged off at Entebbe last week, the push to lift irrigation above 2 per cent of farmland, mechanisation, improved seed, post-harvest storage — requires a farmer to spend money months before earning it.
Without credit, those interventions reach only the farmers who already have cash. Subsidised inputs get captured by the better-off; irrigation stays a demonstration plot; the drying equipment that would fix Teso's aflatoxin problem does not get bought. Credit is the connective tissue, and it is missing for roughly nineteen out of twenty smallholders.
There is also something worth noting about who won. SANDI AI took the female-led grand prize in a competition that deliberately runs separate categories precisely because women founders are under-represented at the top of the funding chain. Ugandan agriculture is disproportionately worked by women who disproportionately do not control the income from it — a pattern documented from cotton in the east to the fisheries of Lake Victoria. A credit-scoring model that reads production activity rather than asset ownership is, structurally, a model that sees women farmers more clearly than a title deed does. Whether it is built to act on that is a design choice, not an inevitability.
The realistic reading of the announcement is modest. A young Ugandan company has won recognition and a small amount of growth capital for tackling the right problem in a plausible way. It has not yet demonstrated the thing that matters — that a Ugandan bank, SACCO or off-taker will lend real money against its score, at scale, and get paid back. That test will take at least two full seasons.
But the alternative approach has now been tried for a very long time. Two decades of credit facilities, guarantee funds and recapitalised development banks have moved the needle remarkably little on the 6 per cent figure, because they treated a supply problem when the binding constraint was an information problem. If a Ugandan startup can make a farmer legible to a lender without a title deed, that is a more consequential change than another Shs100 billion pushed through the same broken pipe. Worth watching, and worth being sceptical about, in that order.



