Written By | Staff Writer
How mining windfalls, a decade-long railway build, and a tourism boom are reshaping East Africa's second-largest economy — even as poverty proves stubborn
BUSINESS
Tanzania enters the second half of 2026 as one of East Africa's most closely watched economies, posting growth rates that outpace most of the continent while wrestling with a poverty rate that has barely moved despite years of expansion. The country's economy grew 6.0 percent in 2025, and the African Development Bank (AfDB), International Monetary Fund (IMF) and World Bank now expect growth of between 5.4 percent and 5.9 percent in 2026, before accelerating again to roughly 6.1 percent in 2027. That combination — strong headline numbers alongside deep structural poverty — makes Tanzania a useful case study in what economic transformation looks like when it is real but incomplete.
A Gold-Fuelled Export Boom
The single biggest driver of Tanzania's recent growth has been gold. Export earnings from the metal reached a record $5.27 billion in the twelve months to April 2026, according to Bank of Tanzania data reported by TanzaniaInvest, making gold the country's single largest foreign-exchange earner and accounting for close to half of all merchandise export revenue. That follows a blistering 2025, when gold exports rose 39 percent year-on-year to $4.75 billion, propelled by a mix of higher global bullion prices and rising output from mines such as Barrick's Bulyanhulu and North Mara operations and Geita Gold Mine.
The mining sector's footprint on the broader economy has grown accordingly. Mining's share of GDP climbed from 9.1 percent in 2023 to 10.1 percent in 2024, and averaged 11.9 percent across the first three quarters of 2025 — a sharp rise for a sector that government planners have long targeted as a lever for diversification away from agriculture. Direct government revenue from mining, collected through royalties, fees and the state's free-carried equity stakes in mining ventures, reached TZS 1.394 trillion (roughly $558 million) in the 2025/26 fiscal year, beating the government's own target by more than 16 percent. Officials have signalled that some of this windfall is earmarked for a new mining development fund intended to extend credit guarantees to small-scale miners and fund mineral research, part of an explicit strategy to link resource revenue to poverty reduction and job creation rather than letting gains concentrate in large-scale operations alone.
Betting Big on Rail: The Standard Gauge Railway
Parallel to the mining boom, Tanzania is in the final stretch of one of Africa's largest ongoing rail infrastructure projects: the Standard Gauge Railway (SGR), a 2,809-kilometre network being built in two phases to replace the country's aging metre-gauge system. Phase one covers 1,219 kilometres from the port city of Dar es Salaam to Mwanza on Lake Victoria; phase two extends a further 1,590 kilometres from Tabora to Kigoma on Lake Tanganyika, with a branch toward Uvinza and Musongati in Burundi.
By March 2026, the Dar es Salaam–Morogoro and Morogoro–Makutupora sections were substantially complete, with passenger services already running — more than one million passengers have travelled on the SGR since commercial service began in June 2024. The Mwanza–Isaka section, the longest remaining stretch at 341 kilometres, had reached 68.77 percent completion, while construction on lot five of the network — being built by Chinese contractors — had reached just over 63 percent. The final leg, the Tabora-to-Kigoma section in western Tanzania, is expected to be finished in 2026, nine years after ground was first broken, and a feasibility study for a further extension toward Mbamba Bay on Lake Nyasa was completed in early 2026. To close out financing for the remaining work, Standard Chartered arranged a $2.33 billion syndicated loan for the government in 2026, one of the largest infrastructure financing packages assembled for a single Tanzanian project. Once complete, the SGR is intended to cut freight transit times from Dar es Salaam to the interior and neighbouring landlocked countries dramatically, reinforcing Tanzania's ambition to be the logistics gateway for the eastern DRC, Rwanda, Burundi and Uganda.
Tourism's Rapid Rebound
Tourism has staged one of the most dramatic recoveries of any Tanzanian economic sector since the pandemic. International tourism revenue jumped roughly 200 percent between 2021 and 2024, reaching $3.9 billion in annual income, while visitor arrivals rose 130 percent over the same period to more than two million people a year. UN Tourism ranked Tanzania the fastest-growing tourism destination in Africa in 2024, citing a 48 percent increase in arrivals compared with pre-pandemic 2019 levels. The sector, anchored by the Serengeti, Ngorongoro Crater, Zanzibar's beaches and Kilimanjaro, now contributes an estimated 10 percent of GDP and roughly 10 percent of national employment, making it second only to mining as a source of foreign-exchange earnings and a critical driver of services-sector job creation in a country where formal employment opportunities remain scarce.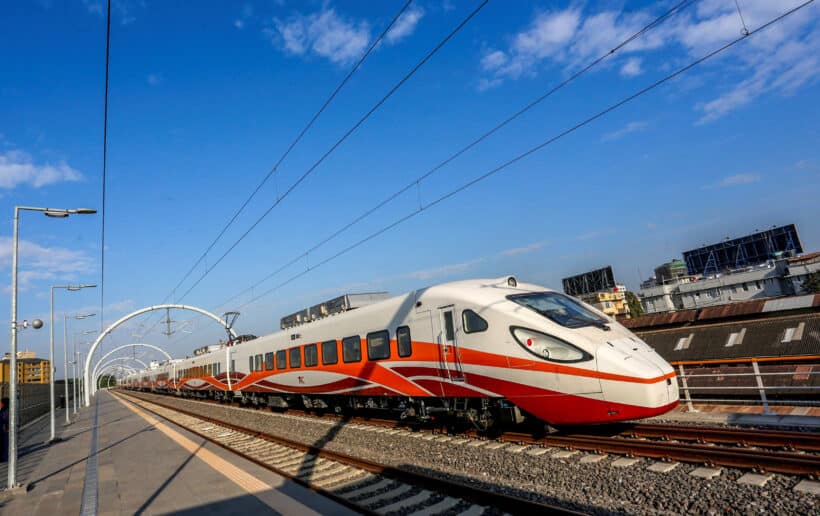
Fiscal Discipline Under an IMF Programme
Tanzania's growth has been underpinned by a multi-year IMF-supported adjustment programme. In July 2026 the Fund's Executive Board approved a disbursement of roughly $443.9 million tied to a combined Extended Credit Facility and Resilience and Sustainability Facility review, alongside a 2026 growth projection of about 6.2 percent, supported by mining, agriculture and tourism. Public debt, which stood at around 49.1 percent of GDP, is projected to edge down to somewhere between 47.4 and 48.3 percent of GDP by the end of 2026, reflecting continued fiscal consolidation. The overall fiscal deficit is likewise narrowing, with AfDB projecting 3.4 percent of GDP for 2026 and more recent IMF assessments pointing to a tighter 2.9 percent. The IMF's most recent Debt Sustainability Analysis, published as part of the Article IV consultation cycle, continues to rate Tanzania at low risk of debt distress, a relatively rare designation in a region where several neighbours are managing active debt-restructuring processes.
Leading the Region on AfCFTA Implementation
Tanzania has also positioned itself as an early mover on the African Continental Free Trade Area (AfCFTA). By June 2025 the country had issued 392 Certificates of Origin under AfCFTA preferential trading arrangements, more than any other East African Community member state, according to reporting in The EastAfrican. Tanzanian exporters shipped goods worth $3.95 billion across the rest of the continent in 2024, spanning sisal fibre, float glass, insecticide-treated mosquito nets, rice, coffee, and fruit and vegetables. That performance comes as intra-African trade overall is forecast to grow 10 percent in 2026, to roughly $230 billion, with manufacturing and agri-food products expected to account for close to half of all intra-African trade flows for the first time. Within the East African Community specifically, regional trade reached $46.3 billion in the first quarter of 2026 alone, with Kenya and Tanzania remaining the bloc's two dominant trading economies.
The Poverty Gap That Growth Has Not Closed
Despite the strength of the headline numbers, poverty reduction has lagged growth. The World Bank estimated in 2025 that 48 percent of Tanzanians live below the $3-a-day international poverty line (in 2021 purchasing-power-parity terms), a figure that has fallen only gradually despite a decade of growth averaging 5 to 7 percent a year. Using a narrower measure, the African Development Bank estimates extreme poverty declined from 41 percent in 2020 to 35 percent in 2025 — meaningful progress, but still leaving more than a third of the population in extreme deprivation. The gap between GDP growth and poverty reduction reflects a familiar pattern across resource-rich African economies: capital-intensive sectors like mining and large infrastructure projects generate substantial fiscal revenue and headline growth, but comparatively few jobs relative to the size of the workforce, while the majority of Tanzanians remain employed in smallholder agriculture, where productivity gains have been slower to materialise.
Outlook
The trajectory into 2027 looks broadly favourable on paper: growth is expected to reaccelerate to around 6.1 percent, gold prices remain elevated, the SGR's final phases are approaching completion, and Tanzania's AfCFTA positioning gives it a head start as continental trade rules mature. The government's challenge is to convert that momentum into broader-based income gains — through the planned mining development fund, continued agricultural investment, and the logistics dividends the railway is meant to unlock — rather than allowing growth to remain concentrated in capital-intensive sectors that touch relatively few Tanzanian households directly. How quickly the poverty rate responds to the current growth cycle will be the clearest test of whether this is a transformation in the full sense of the word, or simply a strong cyclical upswing.



